Why Dana's Credit Card Balance Barely Moved After Three Payments
Dana paid her card every month and still owed almost the same amount. A short case from the classroom shows how statements, interest and minimum payments actually fit together.
The question Dana brought to class
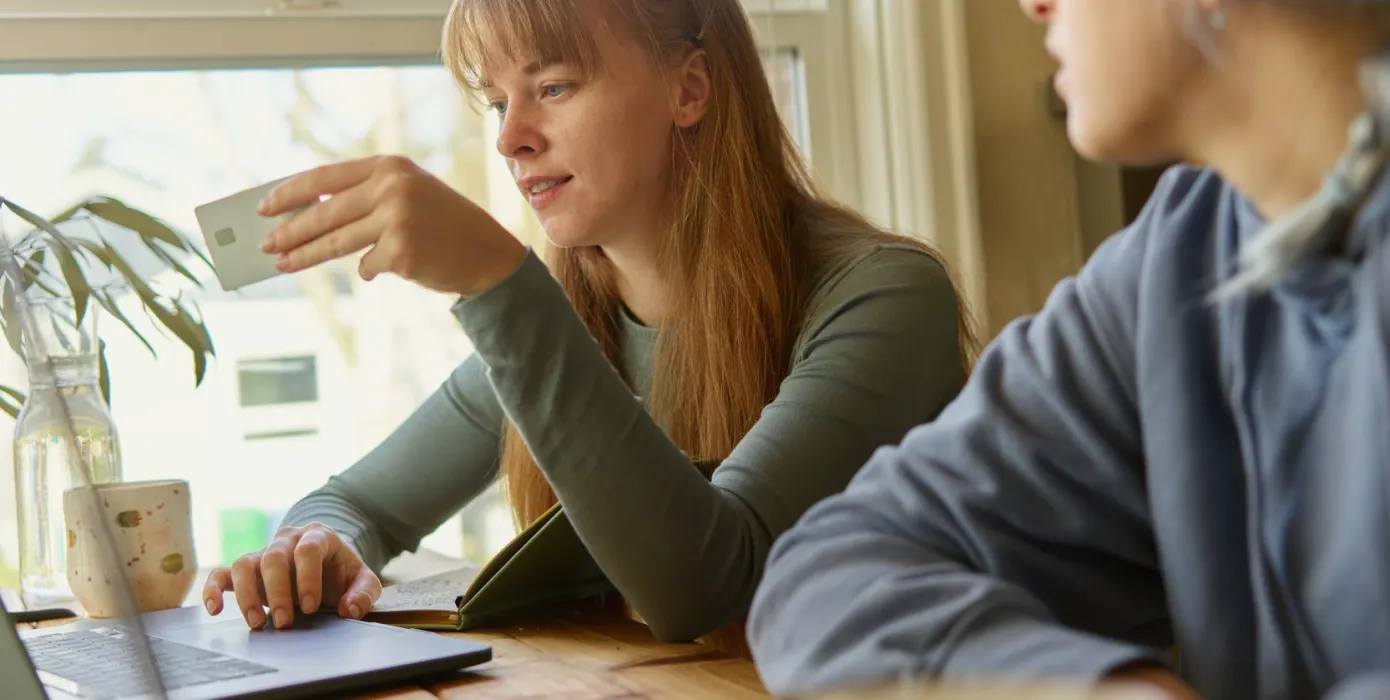
Dana joined one of my evening sessions in the early fall with a printed card statement folded in her bag. She is a dental receptionist in her late thirties, careful with money, and she had been paying her credit card every month without missing a due date. Her puzzle was simple and a little embarrassed: three payments in, the balance had barely gone down.
She had assumed that paying the amount the statement asked for would steadily clear what she owed. Instead the closing balance looked stubbornly familiar. She wondered whether the card company had made an error, or whether she had misunderstood something basic. I told her the second guess was closer, and that she was far from alone. Most of what confused her sat in two small boxes on the statement itself.
We spread the page on the table and went through it line by line, starting at the top rather than the bottom.
What the statement was actually saying
The statement showed a statement balance, a minimum payment, a payment due date and a section for interest charges. Dana had been looking only at the minimum payment, because it was printed in the largest type and was the figure her banking app suggested. Paying it kept her account in good standing, which is why nothing alarming ever happened.
But the minimum is designed to keep an account current, not to clear the debt. A large part of it can go toward the interest charged since the last statement, and only the remainder reduces what she borrowed. On her statement, that remainder was small. New purchases made during the month then added to the total again, so the two movements nearly cancelled out.
I asked her to circle three things: the statement balance, the minimum payment and the interest rate shown for purchases. Seeing them together made the pattern clear without any arithmetic beyond subtraction.
- Statement balance: what you owed when the billing period closed
- Minimum payment: the least that keeps the account in good standing
- Purchase rate: the yearly rate used to calculate interest on carried balances
The grace period she did not know she had lost
The detail that surprised her most was the grace period. Many credit cards in Canada give a window of a few weeks after the statement date during which new purchases carry no interest, but only if the previous statement balance was paid in full. Because Dana had been paying the minimum, she had quietly lost that window.
From then on, interest applied to her purchases from the day she made them, not from the due date. That is why even her small grocery and gas charges seemed to cost slightly more than their sticker price in the long run. Nothing was hidden; the terms were on the card agreement and the statement. They were simply written in a way that is easy to skim past.
I suggested she check her own card agreement for the exact length of the grace period and the conditions attached, since these differ between cards and I cannot read hers from here.
Chip and PIN, limits and what they have to do with it
Dana also asked a question that seemed unrelated: why her card sometimes asked for a PIN and sometimes only a tap. We took a short detour, because it belongs to the same understanding. Chip-and-PIN and tap payments are ways of confirming a purchase; they do not change how the money is owed afterward. A tap under the contactless limit is still a credit card purchase that lands on the same balance.
Her credit limit mattered here too. She had treated it as a spending target, when it is really a ceiling the issuer sets on how much can be owed at once. Staying well below it leaves room for the unexpected and keeps the monthly picture easier to read.
We agreed that the tap habit was fine, as long as she checked her app each week to see what had actually posted rather than trusting memory.
The plan we built on the back of the statement
Rather than aim for a perfect fix, we chose a modest plan Dana could repeat. First, she would pay more than the minimum for the next few months, using an amount she could keep up with after her fixed costs. Second, she would set a calendar reminder two days before the due date, so the payment never rushed through at the last hour.
Third, she would pause non-essential card purchases for one billing period, to see the balance move without new charges on top. None of this required a spreadsheet. It required reading her own statement with a pen in hand.
I should be clear about what this was not. It was not advice about what she should do with her savings, and I did not suggest any product. It was a reading lesson, and the lesson was hers to apply.
- Pay above the minimum when the budget allows it
- Set a reminder before the payment due date
- Compare the statement balance with last month's
What changed by her next class
Two sessions later Dana brought the new statement. The balance had come down by a visible amount, and the interest line was shorter. She did not describe it as a victory. She said the statement no longer felt like a letter written in another language.
That is the outcome I care about in this module. Cards are ordinary tools, and most of the stress around them comes from not knowing which number on the page means what. Once a learner can point to the balance, the minimum, the rate and the due date, the rest becomes a set of small, manageable choices.
Dana still uses the same card. She simply reads the statement the day it arrives, and she knows which box to look at first.
Dana's story is ordinary, which is why it is worth telling. A card statement answers most of the questions people carry around, if you know where each answer sits. The Credit and Debit Cards Explained module walks through statements, interest, limits and chip-and-PIN payments the way we did at that table, one box at a time, with no pressure to buy anything.
You may also like
-
01
How to Build a Monthly Budget You Can Actually Keep ↗
A step-by-step guide to setting up a simple monthly budget around your real income, tracking where the money goes, and keeping the routine going through a busy autumn.
-
02
Five ATM Mistakes People Make and Simple Ways to Avoid Them ↗
Most ATM problems come from small habits: rushing, skipping the screen, or sharing a PIN. Here are five common slips with cash access and plain steps to avoid each one.